For fintech, payments & lending · Reg E · TILA · ECOA aware
In regulated finance, visibility without compliance is a liability.
When borrowers and businesses ask AI who to trust with their money, engines weigh licensing disclosures, clear terms, and credibility signals. Examiners check the same things. We build both at once: AI visibility with copy that survives regulatory review.
Aday Interactive, Inc. is a Coral Gables AI systems firm. We help fintech, payments, and lending companies get quoted accurately by AI engines and pass regulatory review, with public copy built against TILA, Regulation E, ECOA, and state licensing rules.
No credit card, and no obligation.

The new first impression
Customers ask AI before they apply.
ChatGPT, Perplexity and Google’s AI answers now hand customers a short list of names, and they cite the sources they trust. We build so your company is one they can find, trust, and cite by name.

Why this matters right now
Borrowers and buyers now ask AI to explain your product, and it will answer whether its facts are right or not. Three pressures meet here: what AI says about your rates and licensing, marketing that ships faster than compliance review, and trust as the real conversion rate.
- 01AI engines describe your product, accurately or not
- 02Marketing and compliance ship at different speeds
- 03Trust is your conversion rate
AI engines describe your product, accurately or not
When ChatGPT summarizes your rates, terms, or licensing from thin data, a made-up APR or wrong state coverage becomes your UDAAP problem. The fix is structured, authoritative data engines can quote instead of guess.
Marketing and compliance ship at different speeds
Growth pushes copy live. Compliance reviews it later. Trigger-term violations under TILA §1026.24, missing ECOA notices, undisclosed state licensing. Regulators and plaintiffs find each one the way we do: automated scan, sixty seconds.
Trust is your conversion rate
In lending and payments, visitors bounce on the first vague term or missing license number. The disclosure architecture that satisfies examiners is the same one that converts skeptical borrowers.
Run the check. Ask ChatGPT to describe your product, rates, and state coverage. If it guesses wrong, that answer is already in front of your borrowers.
Free estimate · your numbers only
What are the applications that do not fund worth to you?
For value, use your net revenue on a typical funded loan or new account, not the loan amount. Pick your main service, then move the sliders to your own numbers.
Your main service
Each choice loads starting values for that kind of work. They are rough examples, not industry data.
Today
- Funding today
- 100 a month · 1,200 a year
- Not funding
- 900 a month · 10,800 a year
Estimate · if your rate rose
from 10% to 15%
+$360,000 a year
about +$30,000 a month in estimated new net revenue
- Estimated value of all applications that did not convert, 12 months
- $6,480,000
900 a month × 12 months × $600
This is an estimate, not a prediction. Not every one of these is winnable, and we will not tell you what your rate will become. Nobody honestly can. Based only on the numbers you enter. Not a projection, benchmark, or guarantee of results. Nothing you enter is sent to us.
How to read this estimate. It multiplies the numbers you enter, nothing more. It does not count costs, refunds or unpaid bills, seasonal swings, or how much new work your team can take on. The starting values are rough examples, not industry data or results from any firm. This is not legal, financial, or tax advice, and Aday Interactive, Inc. does not promise any result.
The pipeline we ship for this vertical
Start with the free FinTech, Payments & Lending guide
A complete, plain-language guide to compliance-aware intake and lifecycle nurture that respects PCI, KYC, AML, and TCPA. Yours to keep, instantly.
- The full guide, emailed right away and yours to keep
- Then run your free scan to see how AI reads your firm today
- No cost and no obligation


Free · Growth playbook
The FinTech & Lending Growth Playbook
Fifteen one-page plays on applications that get finished, rate and fee pages AI can quote, and follow-up inside TILA, ECOA and Florida texting law. Every play names the rule that applies and gives you three things to do on Monday.
Get the free playbook →How Aday Interactive, Inc. helps
Four disciplines, matched to what your firm needs first.
- 01Become a source AI engines trust to quote Start here
- 02Speed-to-lead that never quotes what it should not
- 03AI adoption built for your next exam
- 04Product experiences with disclosure as architecture

Become a source AI engines trust to quote
We structure your licensing (NMLS), rate presentation, and product terms in the format engines require, so AI names you for high-intent searches and never improvises your APR.
Learn moreSpeed-to-lead that never quotes what it should not
Compliant borrower and merchant intake: AI response in seconds with hard guardrails. No rate promises, no adverse-action ambiguity, ECOA-clean qualification language. Routed to licensed humans at the right moment.
Learn moreAI adoption built for your next exam
Model-risk-aware AI governance, guardrails for marketing AI, vendor due diligence, and documentation your compliance officer can hand to a regulator. Retained fractional AI leadership fluent in UDAAP thinking.
Learn moreProduct experiences with disclosure as architecture
Application flows, rate displays, and dashboards where TILA-required presentation is part of the design system, not a legal patch. Fast, auditable, conversion-tested.
Learn moreCompliance and growth at once
We build the disclosure architecture that satisfies examiners and converts skeptical borrowers in the same pass, not as a legal patch after launch.
Structured data, not guesswork
We give engines authoritative rate and licensing data to quote, so AI stops improvising your APR or your state coverage.
Honest measurement
We architect for accurate AI citation and measure it on a set schedule: Day 30, 60 and 90 on the 90-Day Plan, then monthly if you keep us on hours. We never guarantee a specific AI output, because no honest firm can.
Pricing
What it costs for fintech and lending
Fintech and lending teams usually have a compliance review before anything launches, so work is scoped against it from the start. Your compliance officer keeps final review. Starting floors; your exact number comes from one consultation.
Worked example
A lender that wants AI governance before AI tools
Governance Install (from $12,497): a source registry with named owners, a ratified policy, and a Trust Binder a principal signs. Then Fractional CAIO, Signature (from $3,997 a month), if you want leadership to keep it current.
From $12,497.
Build Scoping credits in full toward the Proof of Concept when you start within 60 days.
Each step is bought on its own; this is an example, not a bundle. Hours, usage, credits, and payment terms are the same for every industry and are on the pricing page.
Related reading
Built for a firm like yours

Who you work with
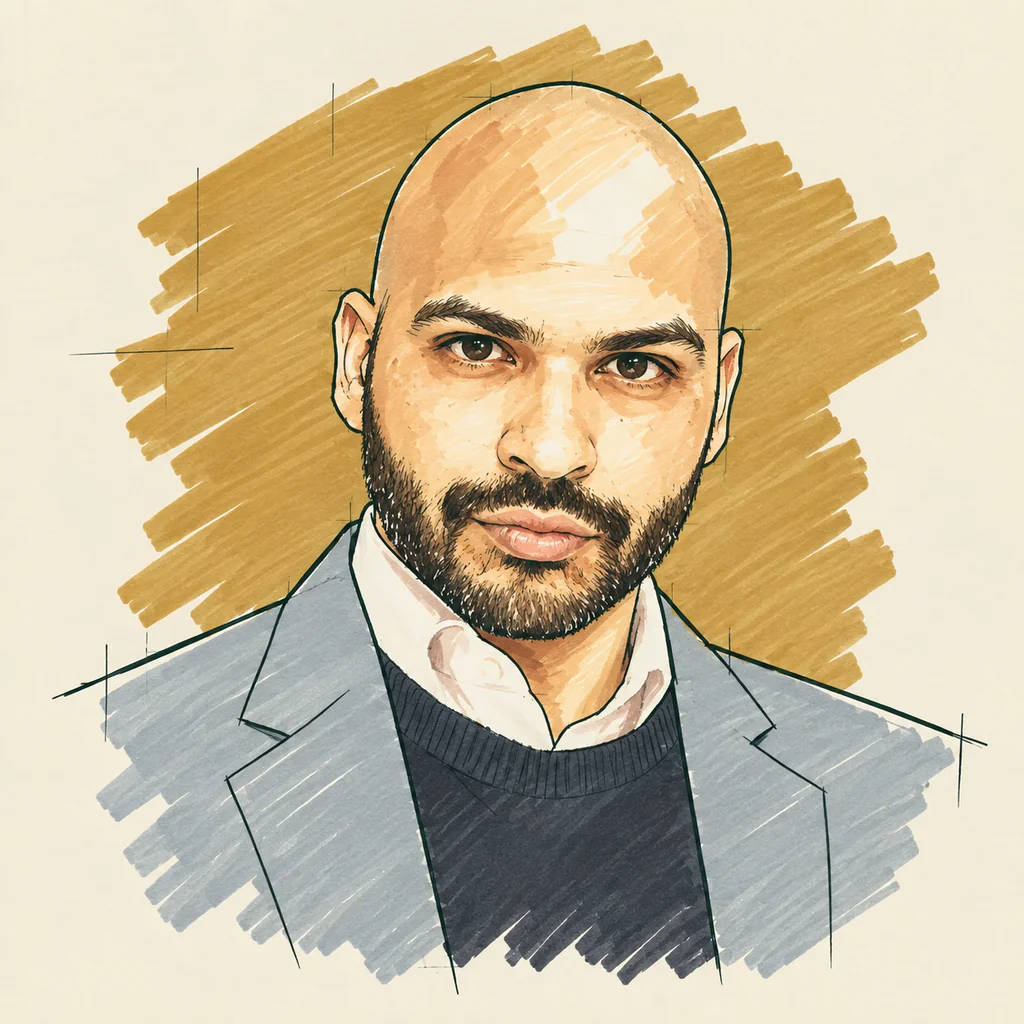
“I help regulated practices get found, trusted, and cited by AI, before it hands their best clients to lesser competitors.”
Brandon Aday, Founder, Aday Interactive, Inc.
Founded the firm in 2002. Seven years at Microsoft Latin America, then digital growth at Univision, Catalina Mobile Payments, and Cascade Financial Technology, and AI work at Southern Glazer’s Wine & Spirits. He leads every engagement personally.
Meet Brandon →Compliance posture
Aday Interactive, Inc. builds marketing and intake systems with reference to TILA/Regulation Z, Regulation E, ECOA, GLBA, UDAAP principles, and state lending-license disclosure requirements. We are not a law firm or compliance counsel of record. Your compliance officer retains final review.
Last reviewed 2026-10.
See what an examiner and an AI engine see
The scan takes about a minute and quotes any trigger-term problem word for word, before you talk to anyone.
Run the free Trust & Disclosure ScanNot ready to talk? Download the free FinTech, Payments & Lending guide.